The Ledger Letter
Finance Studio Advisors · Tuesday, October 13, 2026
 

JPMorgan Earned $15.3 Billion. Wall Street Called It a Miss.

JPMorgan Chase reported third-quarter net income of $15.3 billion this morning, up from $14.4 billion a year ago. Profit grew. The stock market still graded it a failure. Earnings per share came in at $5.57, against the $5.90 analysts expected. That is the problem with this earnings season: the bar is set so high that growth can still disappoint. Tomorrow’s inflation report adds a second test.
 
The Breakdown
Today’s disagreement: JPMorgan’s profit is up from a year ago; the earnings forecast it had to beat assumed much more.
 
01
The Number
JPMorgan earned $5.57 a share, versus $5.90 expected, per LSEG via CNBC. Managed revenue was $50.91 billion, against $51.22 billion expected.
02
The Explanation
Jamie Dimon called it another quarter of strong results. He said trading and investment banking activity moderated somewhat, and the bank cut back on share buybacks.
03
The Bar
Analysts expect third-quarter earnings for the S&P 500 to grow 29.6% from a year ago, per FactSet. JPMorgan’s profit grew about 6%.
A Message From Our Partner
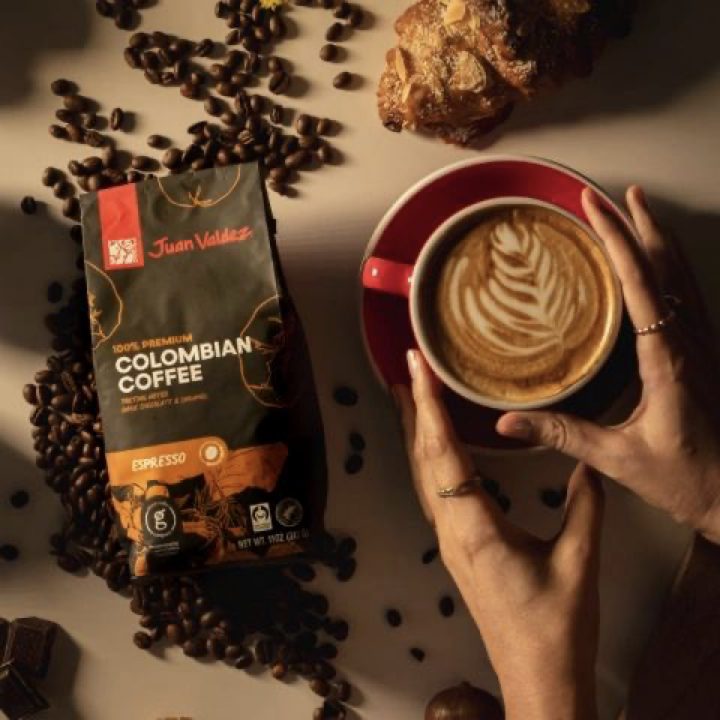
Green Coffee Company
Thirty-five years pricing physical assets taught me one distinction I now use on everything. Stock demand or flow demand.
Gold is stock. Nearly every ounce ever pulled out of the ground still exists, sitting in a vault or a drawer or around somebody’s neck. Demand for it is a decision to hold.
Coffee is flow. It is grown, shipped, roasted, brewed and gone. Seventy-three percent of Americans drink it daily. That demand does not have to be persuaded. It has to be supplied, again, tomorrow morning.
I looked at a private producer this week on that basis.
Green Coffee Company farms 45 properties in Colombia, more than 10,000 acres. Projected harvest this year: 5.1 million pounds of unroasted coffee. Last year: 2.3 million. Milling capacity above a million pounds a week, the largest in the country.
The flow already has somewhere to go. 3,000+ stores. 130+ grocery chains. 21 states. Walgreens live in 1,700 locations. Private label into Carnival Cruise Line, the U.S. National Parks and the UFC. You have very likely drunk the product already without knowing whose farm it came off.
Revenue: $1 million in 2021. $26 million in 2025.
My read. A metal position pays you nothing and asks nothing; you hold it and wait for the regime to change. A flow asset pays you only if the operator keeps executing, every harvest, every shelf reset, every quarter. Different risk entirely. Do not confuse the two because both come out of the ground.
Terms: $1.15 a share, $1,000.50 minimum, no accreditation, up to 20% bonus shares at higher tiers. Unlisted, illiquid, transfers restricted, total loss possible. Size it like growth equity, because that is what it is.
The metal waits for you. The harvest does not.
REVIEW THE OFFERING
Rights apply to retail and institutional sales in the U.S. and Canada (non-cafe business) and are governed by a 10-year agreement to manufacture and distribute the iconic Juan Valdez® brand in the U.S. and Canada. Juan Valdez®, Procafecol S.A., the National Coffee Federation of Colombia, and any of their respective affiliates (collectively, the “Juan Valdez Parties”) are not sponsors, issuers, co-issuers, promoters, guarantors, underwriters, placement agents, or participants in any manner in this investment offering. The Juan Valdez Parties have not reviewed, approved, authorized, endorsed, recommended, or verified this offering, any related offering materials, or any statements made herein, and do not express any view or opinion regarding the merits, risks, or suitability of this investment. Any reference to the “Juan Valdez®” brand or related trademarks is made solely for the limited purpose of describing an existing commercial agreement relating to the manufacture, marketing, and sale of certain coffee products. Such agreement does not extend to, and expressly excludes, any securities offering, fundraising activity, investment program, or capital-raising transaction. Investors should not rely on the existence of any trademark license, brand association, or commercial agreement with the Juan Valdez Parties as an indicator of financial performance, investment quality, creditworthiness, risk mitigation, or likelihood of success of the issuer or this offering. The continuation of any commercial agreement is subject to contractual terms and conditions and may be modified or terminated, and no assurance is given that any such relationship will continue for any period of time. No Juan Valdez Party assumes any responsibility or liability for the accuracy, completeness, or adequacy of the information contained in this offering, nor for any investment decision made by any investor.
 
By the Numbers
JPMorgan EPS, Q3$5.57 vs $5.90 expected
JPMorgan Net Income, Q3$15.3 billion, up from $14.4 billion
JPMorgan Revenue, Q3$50.91 billion vs $51.22 billion
S&P 500 Q3 Earnings Growth, Expected29.6%
September CPI Forecast, Due Wednesday3.7% y/y, core 2.5%
JPMorgan figures per the company’s October 13, 2026 filing and CNBC, estimates per LSEG. S&P 500 estimate per FactSet. CPI forecast per Reuters.
A Message From Our Partner
Dear Friend,
In a recent interview, Musk laughed nervously and said seven words most people scrolled past: “You need transformers to run transformers.”
That wasn’t a joke. It was a confession.
His supercomputer runs on power equipment that takes 120 weeks to build.
He built Colossus in 122 days.
The gap between those two numbers is the biggest bottleneck in the entire AI buildout. And it’s where the money is.
For you, that gap is the opening: one small American company closes it faster than anyone alive.
The press is chasing rocket launches and missed it.
Wall Street still prices it like an afterthought. That won’t last.
SEE THE STOCK MUSK’S OWN WORDS POINTED TO >>
“The Buck Stops Here,”
Kelly Maguire
Behind the Markets
© 2026 Behind the Markets. 4260 NW 1st Avenue, Suite #55 · Boca Raton, FL 33431. LEGAL DISCLAIMER: Personal results may vary. All investing involves risk of loss. Past performance is not a guarantee of future results. The information provided is for educational purposes only and does not constitute a recommendation to buy or sell any specific security.

When Growth Counts as a Miss

What the Headlines Lead With

Most coverage this morning leads with the miss, and it is a rare one. JPMorgan usually beats. Last quarter it earned $6.14 a share against a $5.59 estimate.

This time the shortfall came from Wall Street businesses. Dimon said trading and investment banking moderated. Global investment banking revenue fell 6.6% from a year earlier, per Dealogic data cited by CNBC.

Wells Fargo also reported before the open, with mixed results. Goldman Sachs reported shortly after, and Citigroup is also on today’s schedule.

Why Profit Up Can Still Mean Down

Stock prices move on the gap between results and expectations, not on results alone.

Before the report, analysts expected JPMorgan’s earnings per share to grow about 17%, per TipRanks. Actual growth came in near 10%. That is solid for most companies and short for this one.

Options traders had priced a move of roughly 3.6% in either direction around the report. That tells you how much was riding on a single number.

Our view: this season will reward companies that beat a very high bar and punish companies that merely grow. Investors who own the index own that risk across hundreds of names.

What It Means for Your Money

Banks are an early read on the consumer. Their comments on loan losses and card spending will matter more than one quarter of trading revenue.

JPMorgan alone held $5.1 trillion in assets at the end of September. Its view of household credit carries weight well beyond its own stock.

For index investors, the bigger question is the 29.6% forecast for the S&P 500. Much of that growth is expected from AI-related companies. Banks reporting softer trading do not change that, but they do show how little room there is for disappointment.

The buyback cut matters too. Buybacks support a stock’s price. Less buying from the company itself leaves the share price more exposed to outside sellers.

The Day Ahead

Dimon and his team hold their call at 8:30 a.m. Eastern. Listen for comments on credit quality and on whether trading softness continued into October.

September CPI lands Wednesday at 8:30 a.m. Economists expect 3.7% headline inflation and 2.5% core. A hot core number on top of a bank miss would test this market from two directions at once.

Worth watching: how bank stocks trade after the call. A recovery by the close would say investors care more about credit quality than one quarter of trading revenue.

From Our Partner
The IRS gets notified the moment most assets change hands.
Profit is a fact. A miss is an opinion about what the fact should have been.

Recommended for you

View all
caret-right